
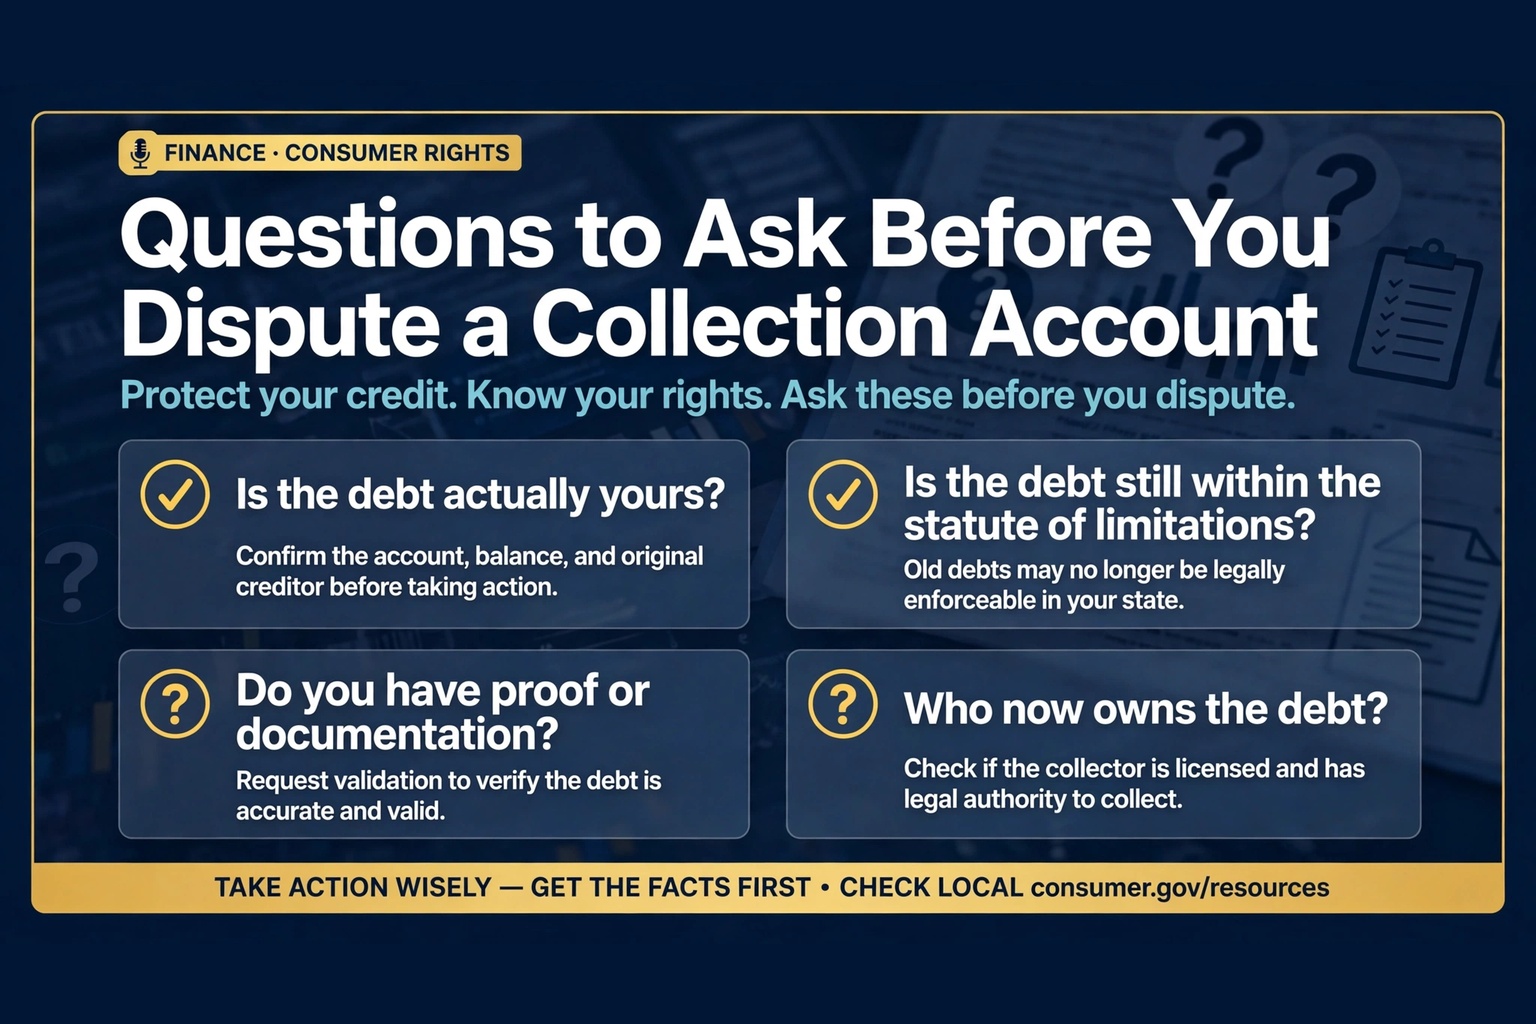
Before you dispute a collection account, slow down and ask a few questions. The answers decide whether a dispute helps your credit or just wastes your one clean shot at getting the record corrected.
First, is the debt actually yours, and is the amount right? Pull your reports from all three bureaus and compare the balance, the dates, and the original creditor. Second, is the account still inside the reporting window? Most negative items age off after seven years. Third, do you have documentation — statements, letters, payment records — that proves your side?
If the information is inaccurate, incomplete, or cannot be verified, dispute it in writing with the bureau reporting it, keep copies of everything, and give the investigation the full 30 days. Accuracy is the standard the law sets; make the collector and the bureau meet it.


Join the conversation
Load Facebook comments to read and reply using your Facebook account.